

B9: Cash Advance
by B9 - Get Your Paycheck Early
4.6
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.6
- Price
- Free
- Download
- 1.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
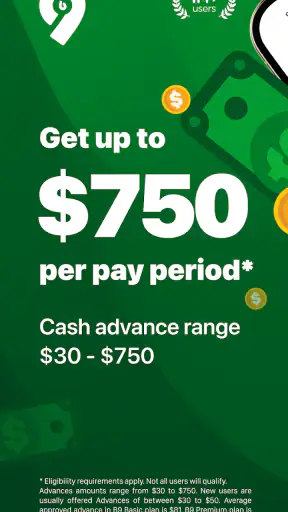
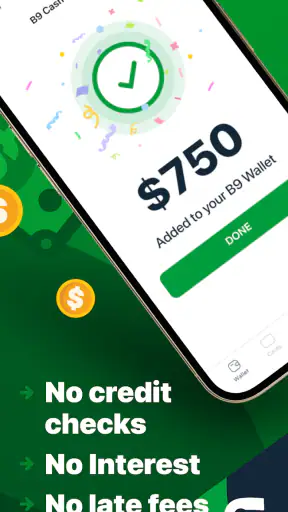
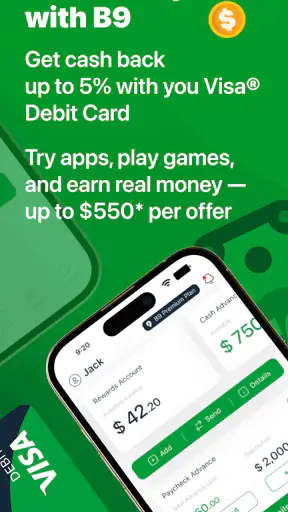
 Analysis by Getfullapps
When an unexpected bill lands between paydays, the problem is often not long-term income but timing. B9: Cash Advance is built around that narrow problem: it is a finance app from B9 - Get Your Paycheck Early that lets eligible users seek access to part of their paycheck before the normal payday. I see it as a short-term cash-flow tool rather than a replacement for budgeting, saving, or a conventional bank account.
That distinction matters. An early paycheck can be useful when a bill, transport fare, grocery run, or household expense arrives at the wrong moment. It can also become an expensive habit if every payday starts with money already committed. After looking at the app through that lens, I think the main question is not whether early access sounds convenient. It is whether your income pattern is steady enough, and your repayment plan clear enough, for the convenience to solve a temporary timing issue without creating another one.
How I Would Decide Whether B9 Fits
I’d judge B9 by whether it makes a rare timing problem easier without becoming part of my regular payday routine. I’d first check that the specific expense is necessary, then confirm the amount and repayment fit comfortably around the next pay cycle. That small pause helps distinguish a useful backup from a habit that quietly narrows future choices.
Start with the problem, not the advance
Before installing any paycheck advance service, I would write down the exact amount needed and the date it must be paid. That simple step helps separate a genuine timing gap from a recurring shortfall. B9 is most appealing in the first situation. If I know my next paycheck is coming and I only need to bridge a few days, an early-access service may be more practical than missing a payment or relying on a credit card.
If the same gap appears every pay period, I would be more cautious. An advance can make the current week feel easier while leaving less money for the following one. In that case, a revised bill schedule, an emergency fund, a conversation with the service provider, or a traditional credit option may address the underlying issue better. The app can help with timing; it cannot make an income that is too small cover a larger set of regular expenses.
Check the practical fit before depending on it
I would also treat eligibility and access as something to verify inside the app before making a promise to a landlord, utility company, or family member. Financial apps commonly need information about the user and their income arrangement to determine whether the service works for them. That means I would not plan an urgent payment around an advance until I had completed the setup and understood the available amount, arrival process, and repayment timing shown in my own account.
This is one of the most important habits with B9: use it as a possible option, not as guaranteed money. A store description can explain the purpose of an app, but only the in-app experience can tell you whether your personal situation is supported. I would install it before the emergency, not while a payment is already overdue, so there is time to read each screen carefully.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
Read the money details as carefully as the amount
The word “free” in the app listing refers to downloading the app, not to assuming every financial service connected with it has no conditions or cost. I would inspect the complete advance terms, any applicable fees, the repayment date, and what happens if my paycheck arrives later than expected. I would also look at whether optional services are clearly separated from anything required.
For me, the best test is straightforward: if I cannot explain in one sentence how much I receive, how much I owe back, and when the money leaves my account, I am not ready to use the advance. That rule is more useful than focusing on the headline amount because a small, unclear obligation can still disrupt the next pay cycle.
A realistic everyday use case
Imagine that I am paid regularly, but my phone bill and a necessary prescription fall just before payday. I could use B9 to investigate whether an advance is available, compare the total repayment with the cost of missing the bill, and take only what closes that specific gap. Once paid, I would record the repayment in my budget as money already spoken for.
The important part of that workflow is restraint. I would not take the maximum simply because it is offered, and I would not use the extra money for discretionary shopping. I would also leave enough in the next paycheck for rent, food, transport, and other fixed commitments. In my view, that is where the app’s usefulness is decided: not at the request screen, but in the plan for the following payday.
Where the app is strongest
B9 has a clear focus, and that focus is its biggest strength. Instead of asking me to manage a broad collection of financial products, it centers the experience on getting paid earlier. For someone who already understands their cash flow, that narrow purpose can feel easier to act on than opening a credit card, applying for a personal loan, or moving money between several accounts.
It is also a better conceptual match for a short-lived timing problem than a long repayment product. A conventional loan can be excessive when the need is limited to the days before a known paycheck. A credit card may solve the immediate purchase but can leave a balance that is easy to carry forward. B9 belongs to a different category: the goal is to bring part of expected earnings forward, then account for that reduction later.
The app is free to download and is listed for everyone, which makes it approachable for people who want to explore the service without paying an upfront app price. It has also reached more than a million installs, with a 4.6 average from around eighteen thousand ratings and roughly seven thousand four hundred written reviews. I do not treat popularity as proof that it will work for me, but that level of use suggests the basic idea is familiar to a substantial audience.
Small decisions that make the experience safer
One useful habit is to keep a separate note of every advance request, including the purpose and the expected repayment date. This prevents a common mistake: remembering the money received but forgetting that the next paycheck is smaller. I would update the note immediately after using the service rather than waiting until payday.
A second habit is to compare the advance with non-borrowing alternatives first. Could the bill be moved by a few days? Could I delay a nonessential purchase? Could I use money already saved for emergencies and replace it on payday? If one of those options avoids a new obligation, it may be the cleaner choice. B9 is most valuable when those alternatives are unavailable or more damaging, not when it becomes the automatic first button for every inconvenience.
A third is to test the app during a calm week. I would review the account screens, notifications, repayment information, and support path before I needed urgent help. That preparation reduces the chance of accepting a term too quickly under pressure. It also tells me whether the interface makes the important details easy to find, which is especially important in a finance app.
What may feel limiting
The same narrow focus that makes B9 simple can make it unsuitable for broader financial planning. It is not the tool I would choose to build a monthly budget, compare savings accounts, consolidate debt, or plan a long-term emergency fund. Someone looking for a complete money-management dashboard may get more value from a budgeting app or their bank’s own financial tools.
There is also a behavioral limitation. Early access changes the timing of income, but it does not increase the total amount earned. If I use it repeatedly, I may begin to treat part of every paycheck as available before it arrives. That can hide an unstable budget and make ordinary expenses feel like emergencies. The app deserves a place in a careful plan, not a permanent role in one.
Another point of friction is the need to understand personal eligibility and timing before relying on the service. I would not assume that installing the app guarantees an advance, that the same amount will always be available, or that funds will arrive at the exact moment a bill is due. Those are practical questions I would answer from the account’s current information and terms, not from a general expectation about paycheck apps.
How it compares with the usual alternatives
Compared with a credit card, B9 may be more focused when the need is specifically to bridge the period before income arrives. A credit card is more flexible for purchases and can remain available for repeated spending, but that flexibility can encourage a balance to linger. I would favor the card when I need purchase protection or a payment method accepted by a merchant, and consider B9 when the issue is access to expected wages.
Compared with a personal loan, the app appears better aligned with a smaller, short-term timing problem. A loan may make more sense for a planned expense that cannot be covered by one paycheck, especially when a structured repayment schedule is important. I would avoid using either option for routine overspending, but I would be especially careful with a loan because extending the repayment period can make a temporary problem last much longer.
Compared with an overdraft or an informal loan from someone I know, B9 offers a more organized digital route to investigate an advance. Still, the right choice depends on the actual terms and the consequences of each option. An overdraft may be convenient but can trigger bank charges; borrowing from family may avoid a formal financial product but can strain a relationship. I would compare the total cost, timing, and repayment pressure instead of choosing based only on speed.
Compared with an employer-based wage access benefit, B9 may be worth considering when that workplace option is unavailable. If my employer already provides an early-pay feature with terms I understand, I would compare it directly before adding another service. Fewer moving parts can be preferable, especially when the employer route connects more naturally to payroll. The better alternative is the one that gives me clear timing and a repayment obligation I can comfortably absorb.
The cost of changing your routine
Switching to an advance app is not only an installation decision. It can change how I schedule bills, how much I leave in my account, and how I think about the next paycheck. Before using B9 regularly, I would revise my budget so the repayment is visible alongside rent, utilities, food, transport, and subscriptions. If the numbers only work when I take another advance, that is a warning that the routine is not sustainable.
I would also avoid stacking several short-term solutions. Using B9 while carrying a credit-card balance and an overdraft can make the calendar look manageable even though the next income payment is already divided among multiple obligations. One advance for one defined problem is easier to monitor than several overlapping commitments.
For a user who decides to stop, the sensible approach is to let the current obligation finish, remove the advance from the regular budget, and rebuild a small cash buffer with whatever amount is now available. The goal is not to remain dependent on any early-pay service. The goal is to make the service unnecessary whenever possible.
Who should use it, and who should skip it
I would recommend exploring B9 to a person with predictable pay, a clearly identified short-term gap, and enough room in the next paycheck to cover the repayment without sacrificing essentials. It may also suit someone who wants a dedicated early-pay option rather than a revolving credit line, provided that the terms are understood before accepting anything.
I would tell someone with irregular income, frequent unpaid bills, or no room in the next pay cycle to pause. The app may not solve the real problem, and depending on an advance could deepen it. I would also steer away from using it for entertainment, impulse purchases, or expenses that will recur every month. Those situations call for a spending adjustment or a longer-term financial solution.
The app runs on Android versions from 8.0 onward, so I would check the operating system before planning around it. B9 - Get Your Paycheck Early lists the current release as version 3.70.0, and the app was released on August 3, 2021. Those details are useful when checking compatibility, but they do not replace reading the current account terms or confirming that the service fits my circumstances.
My recommendation after weighing the trade-offs
My view is positive but deliberately limited: B9 is worth considering as a controlled bridge between a known paycheck and a time-sensitive expense. Its purpose is easy to understand, its download price is free, and its strong user response gives it a reasonable starting point for investigation. I like the idea more when the user takes only what is needed and treats repayment as part of the original purchase.
I would not present it as a universal answer to financial stress. If the same shortage keeps returning, I would choose budgeting help, employer resources, savings, bill negotiation, or a more suitable credit product before making early access part of my routine. The app is at its best when it handles an occasional mismatch between payday and due date.
My practical recommendation is to install B9 before an emergency, inspect the exact terms available to you, and write down the full repayment plan before accepting an advance. If that plan leaves your next paycheck comfortable, the app may be a useful safety valve. If it leaves essentials uncertain, skip the advance and look for a solution that fixes the monthly cash flow rather than moving the same pressure a few days forward.
Pros
- Quick access to cash advances for eligible users
- No traditional credit check is required to apply
- Repayment is usually handled automatically on payday
- Clear app interface makes borrowing easy to understand
- May help cover unexpected expenses between paychecks
Cons
- Advance limits may be low for new or infrequent users
- Eligibility depends on income, payroll, and account activity
- Optional fees can increase the total cost of borrowing
- Automatic repayment may strain your next paycheck
- Availability and features vary by employer and location
FAQs for B9: Cash Advance
What is B9: Cash Advance, and how does it work?
B9: Cash Advance is a financial app designed to give eligible users early access to part of their earned income, depending on the service and account terms available to them. After signing up, you may need to verify your identity and connect qualifying payroll information. The amount, timing, eligibility requirements, and repayment process can vary, so review the current terms carefully before requesting an advance.
How much money can I receive through B9: Cash Advance?
The amount available through B9 is not necessarily the same for every user. Your potential advance may depend on factors such as verified income, payroll history, account activity, employer information, and other eligibility checks. The app should display the amount you qualify for before you confirm a request. Avoid assuming that the maximum advertised amount will be available immediately or on every pay cycle.
Are there fees or subscription costs associated with B9?
Before downloading or requesting money, users should examine B9’s current pricing information because costs may depend on the membership plan, transfer speed, and selected features. Some services may include a recurring subscription, optional instant-transfer charges, or other account-related fees. The final cost should be shown in the app before confirmation, but terms can change, so always read the fee schedule and cancellation conditions.
How quickly can a B9 cash advance reach my bank account?
Delivery time depends on the transfer method, your bank, account verification status, weekends or holidays, and whether you choose a standard or faster option. Some users may receive funds quickly, while others could experience delays if additional verification is required. B9 does not guarantee that every advance will arrive instantly, so check the estimated arrival date and any applicable fee before submitting the request.
Is B9: Cash Advance safe, and what information is required to use it?
B9 may request personal, identity, employment, payroll, and banking information to verify eligibility and process financial services. Before using the app, confirm that you are downloading the official version from a trusted store and review its privacy policy, security practices, permissions, and account terms. Never share login codes or sensitive information outside the official app, and contact support if activity on your account looks unfamiliar.

B9: Cash Advance
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via support@bnine.com, visit https://bnine.com, or review their https://bnine.com/privacy-policy.










